The platinum group metals, or PGMs, consist of platinum, palladium, rhodium, iridium, ruthenium and osmium. They have similar physical and chemical properties and tend to occur, in varying proportions, together in the same geological deposit. The usefulness of PGMs is determined by their unique and specific shared chemical and physical properties.
The PGM elements of the periodic table
While certain of these properties are shared by other materials, it is the particular combination of their chemical and physical properties that makes the PGMs so valuable in their end-markets. PGMs have high and specific catalytic activity, possess high thermal resistance, are chemically inert and biocompatible, as well as being hard but malleable for forming into shapes.
Platinum, palladium and rhodium are used in higher-volume industrial and medical applications, while iridium and ruthenium have niche high-technology applications.
The attractive properties of the PGMs make them all the subject of intensive ongoing research and development into novel end-uses.
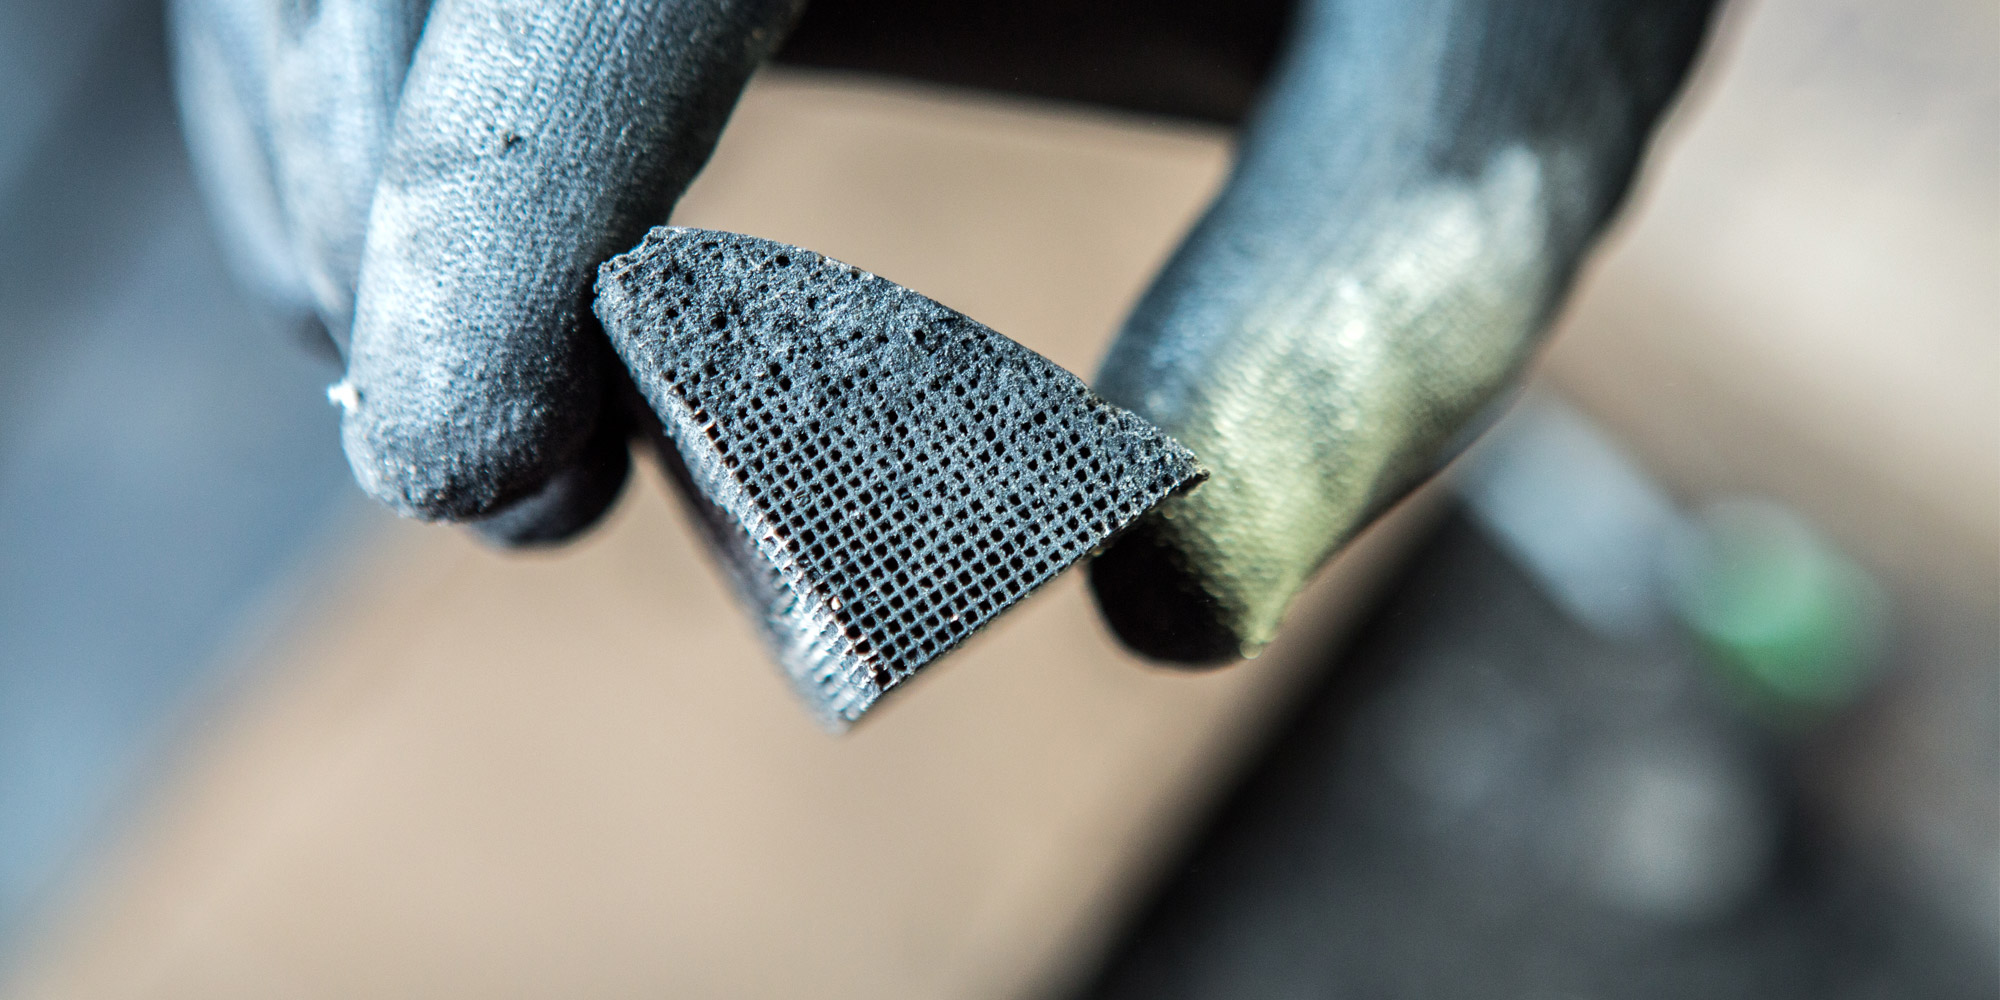
The automotive sector is the leading end-user for platinum, palladium and rhodium. The unique properties of PGMs help convert harmful exhaust pollutant emissions to harmless compounds, improving air quality and thereby enhancing health and wellbeing. All three metals are used in varying proportions in autocatalysts, which form part of the automotive exhaust systems of both gasoline and diesel internal combustion engines (including hybrids) in light-and heavy-duty vehicles, both on- and non-road. PGMs have accordingly been the main metals used in catalytic converters to date since the imposition of emission controls.
Vehicle exhaust emission controls began in the US in 1975, with the use of PGM-containing catalysts on light-duty vehicles. Subsequently, most other countries adopted similar legislation, notably Japan (1976), South Korea (1987), Mexico (1989), Europe (1993), Brazil (1994) and China (2000). Over time, emissions standards have continued to tighten globally, resulting in higher loadings of PGMs per catalyst in most instances, or else varying formulations and technologies, to ensure compliance with regulations. The trend for ever-higher loadings is beginning to level off, as catalyst coating technology continues to improve (so less metal is required to achieve the same effect) and as emissions standards focus more on ensuring compliance with legislation, rather than adding evermore challenging targets.
Despite PGM price volatility, platinum, palladium and rhodium face little foreseeable competition in autocatalysts, although substitution of one PGM for another is widespread, driven by pricing and supply constraints.
An increasingly viable low-emission alternative to the combustion engine exists in the shape of the battery electric vehicle which requires no autocatalyst and hence no PGM after-treatment.
While the hydrogen economy holds great potential for using green hydrogen in certain industrial applications, fuel cell technologies are not expected to comprise a large share of the future light vehicle market, though the outlook may be slightly stronger for some heavy-duty vehicle applications. Rapid and substantial improvements to battery electric vehicle technology are overcoming issues such as range anxiety and charging time, which previously may have favoured a higher share of hydrogen fuel cell powertrains.
OUR 2025 6E PGM
production basket
(Excluding 3E PGM
recycled ounces)
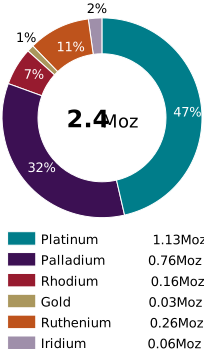
Source: Sibanye-Stillwater disclosure
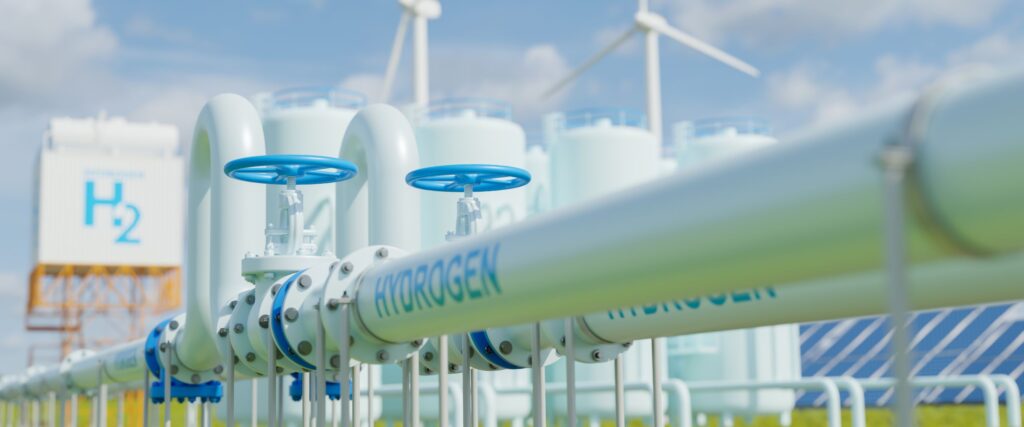
The emerging hydrogen economy is expected to rely on several of the PGMs, principally platinum, ruthenium and iridium, to catalyse its processes.
Investment is one of the drivers of demand for PGMs, particularly platinum. Investment demand ranges from physical holdings of bullion bars and coins to complex investment vehicles, through exchange-traded funds (ETFs) and the futures markets. Physical investments, along with global stocks, are treated as above-ground stocks that are not considered as an end-use as they could be either allocated or returned to the market, depending on price levels and investor strategy.
Information above provided by SFA (Oxford)
Learn more about each of the PGMs

Platinum

Palladium

Rhodium

Ruthenium