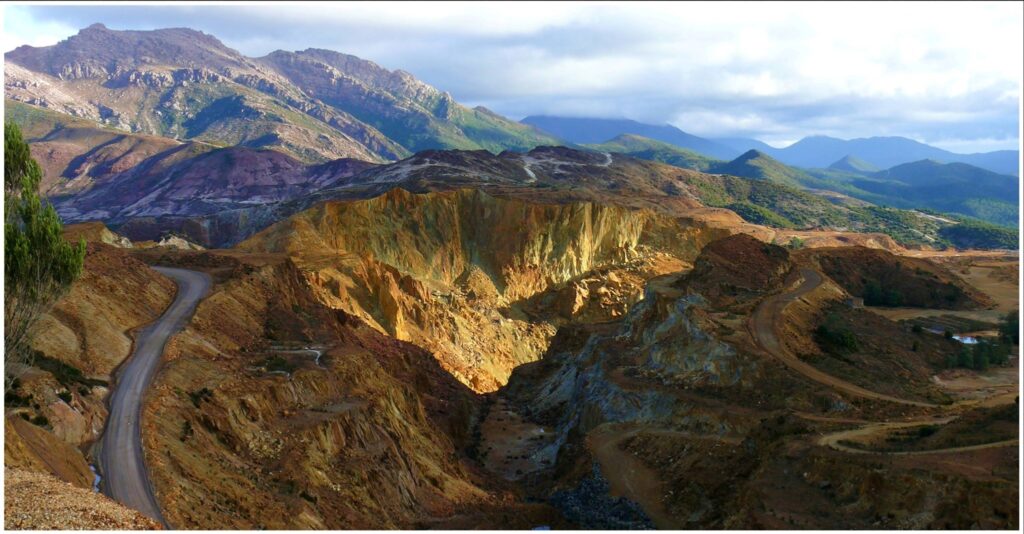
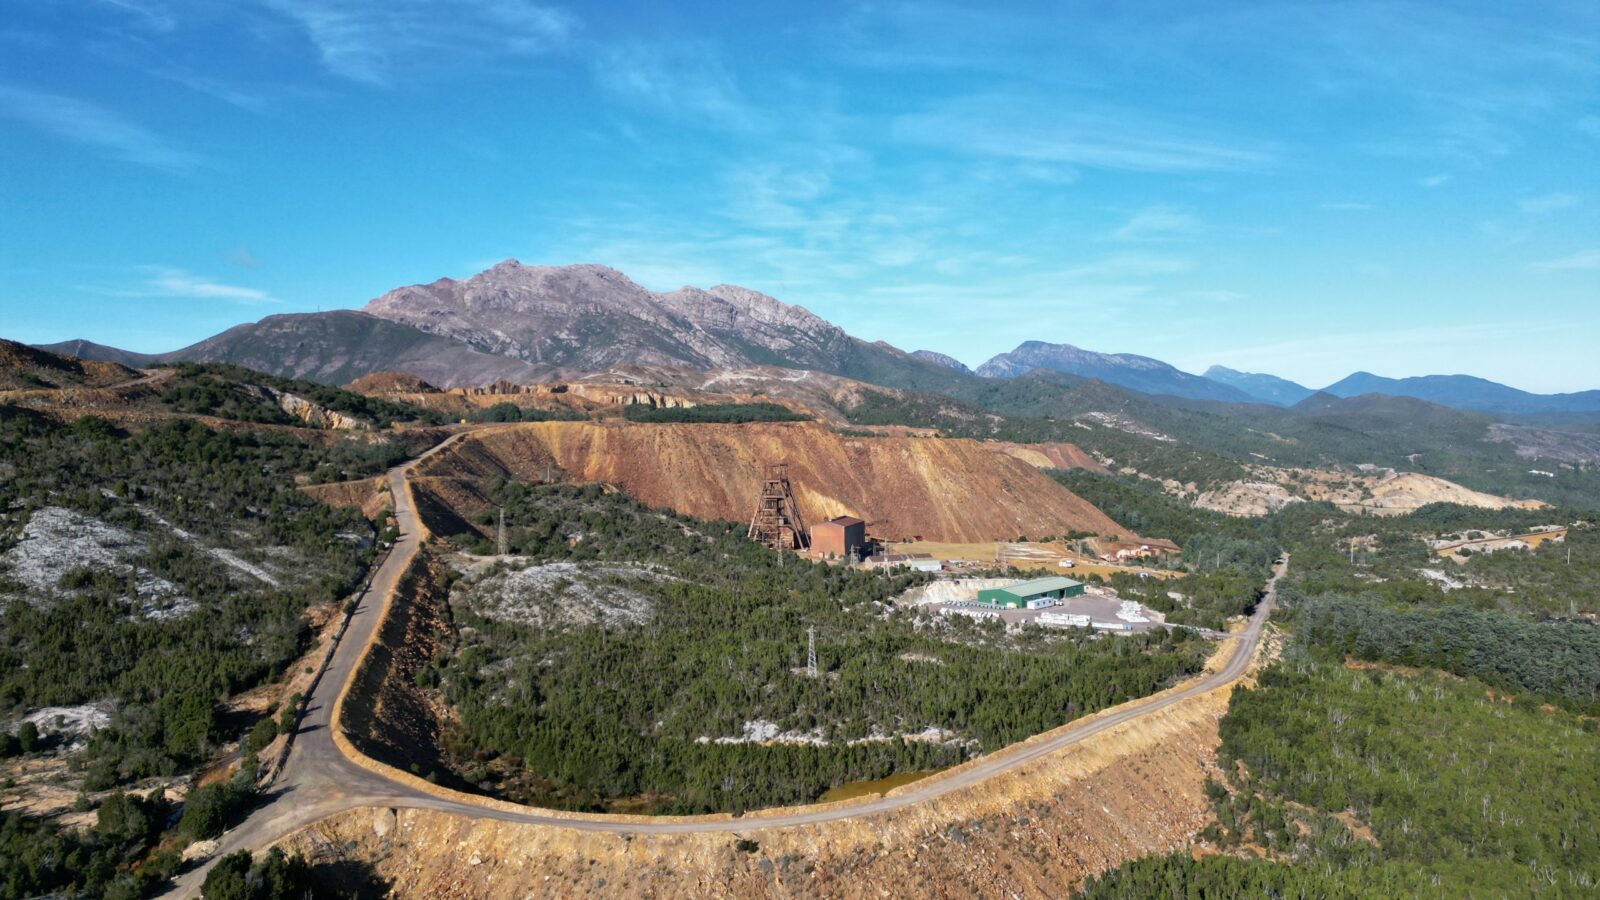
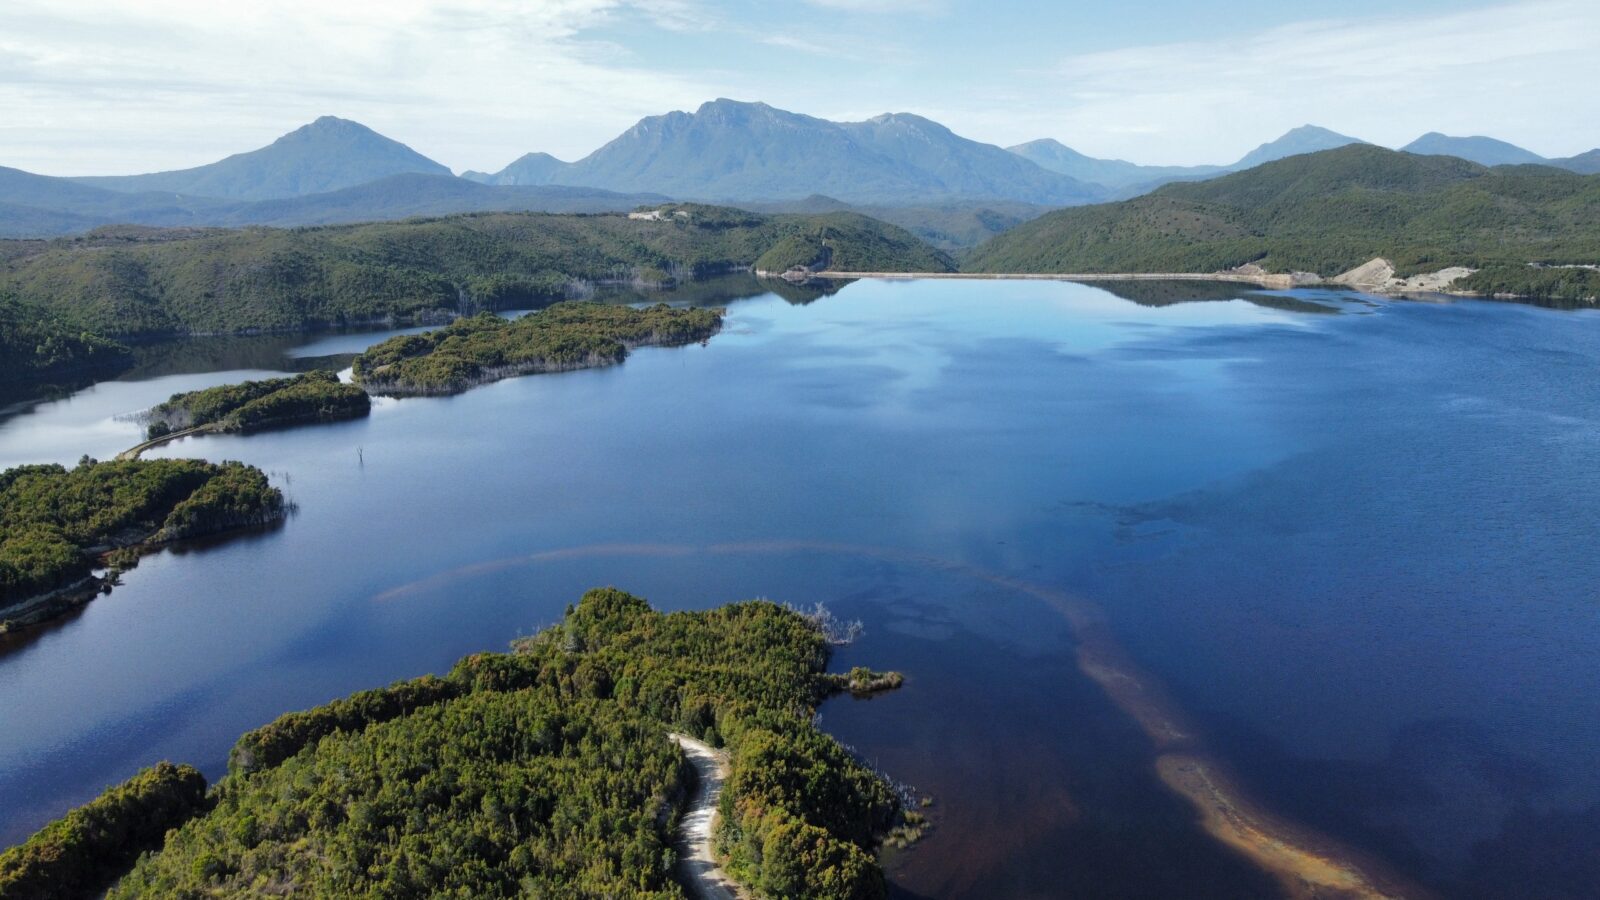
Mt Lyell is a near-term restart of a long-life copper-gold project near Queenstown, Tasmania. The brownfield project benefits from substantial existing infrastructure and established operating knowledge, with first production targeted for early 2029.
Expected statistics at steady state
Life of mine

23 years
>26kt
copper annually
at steady state

>16koz
gold annually
at steady state
~116koz
silver annually
at steady state

Workforce
>300
employees and contractors
Following completion of an AACE Class 2 feasibility study and an internal assurance review, the Mt Lyell copper-gold project received Board approval to proceed in Q3 2026. The approval advances a long-life brownfield asset aligned with Sibanye-Stillwater’s strategy to unlock value from internal organic opportunities and its disciplined capital-allocation framework.
Project execution is planned to commence in H1 2027, with first metal production expected in early 2029. At steady state, Mt Lyell is expected to produce approximately 26kt of copper, 16koz of gold and 116koz of silver annually.
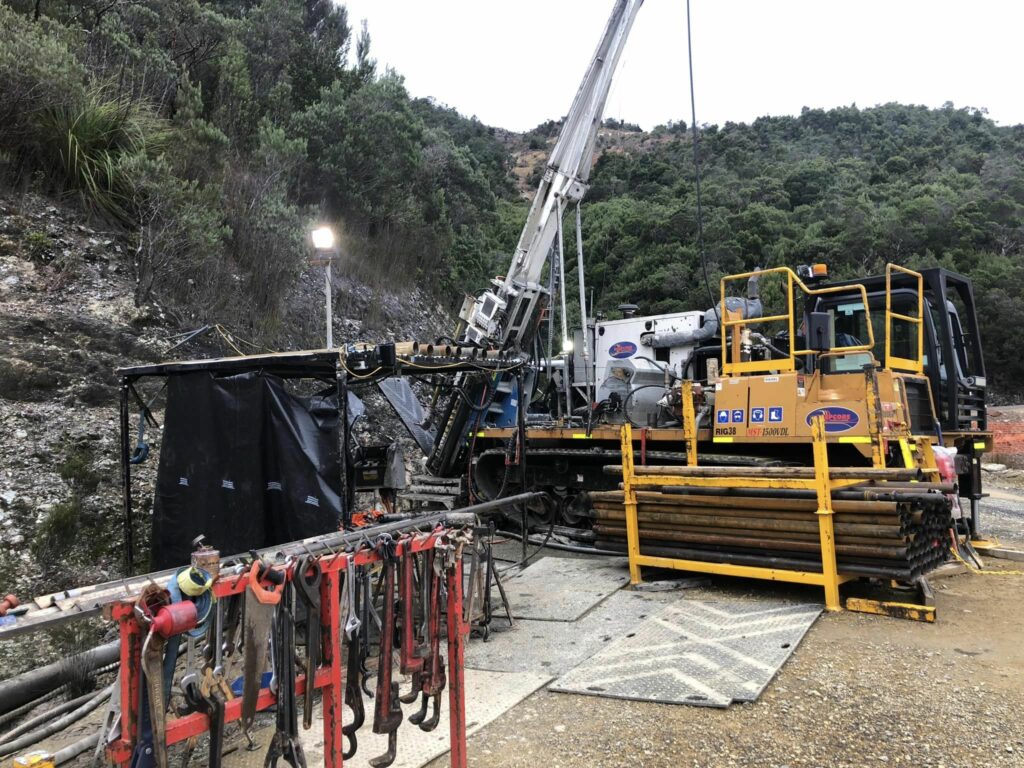
Mt Lyell has a 79.4Mt Mineral Resource containing 1,609Mlb of copper and 0.5Moz of gold across various underground and open pit deposits. All leases are 100% held by Copper Mines of Tasmania (CMT) which is a wholly-owned subsidiary of Sibanye-Stillwater, including significant infrastructure and underground development underpinning the potential brownfield development.


A closer look
| Metric | Current project basis |
|---|---|
| Average all-in sustaining cost | US$2.56/lb |
| Post-tax net present value | ~US$550m (~A$790m) at a 7.4% discount rate |
| Post-tax internal rate of return | ~20% |
| Total project capital to practical completion | ~US$340m (A$490m) |
| Maximum cash draw | ~US$370m (A$530m) |
| Anticipated cost position | Second-quartile C1 costs |
- Expands the Group’s exposure to copper through a long-life brownfield asset in a Tier 1 jurisdiction
- Uses existing infrastructure, mine access, underground development, tailings infrastructure and established logistics, reducing execution complexity and upfront capital relative to a comparable greenfield development
- Draws production from multiple orebodies, providing operational flexibility and reducing reliance on a single production area
- Uses proven mining and processing methods and has access to renewable hydropower
- Supports the Group’s future-focused metals strategy without an acquisition premium and will be advanced through disciplined, stage-gated execution
- The project is expected to employ approximately 300 people at steady state
- Local employment, procurement, training, housing and community integration will form part of implementation and stakeholder-engagement plans
The project has been substantially de-risked through feasibility and assurance work, with defined technical, permitting and operational-readiness activities continuing through execution. Projects in the Group’s portfolio will continue to be sequenced according to returns, affordability, readiness and strategic fit, balancing shareholder returns and balance-sheet strength with investment in future production and portfolio quality.
Total capital expenditure guidance for 2026 is A$11 million (US$7.5 million/R136 million).
Sibanye-Stillwater will be responsible for meeting environmental, rehabilitation, and closure obligations that arise from both the restart and future operations, in accordance with applicable regulations. The Group is currently evaluating opportunities such as mine-water treatment and reuse, progressive rehabilitation, and the engineered placement of potentially acid-forming material in suitable existing mining voids.
Access to renewable hydropower is expected to reduce the carbon intensity of production.
References
- Mineral Resources and Mineral Reserves report 2025
- Media release, 1 Nov 2023: Sibanye-Stillwater exercises its option on the Mt Lyell copper mine and gives notice to shareholders in terms of Section 45(5) of the Companies Act
- Media release, 27 Oct 2021: Sibanye-Stillwater invests further in the circular economy as it expands its tailings retreatment exposure through a 19.99% investment in New Century Resources
Contact us